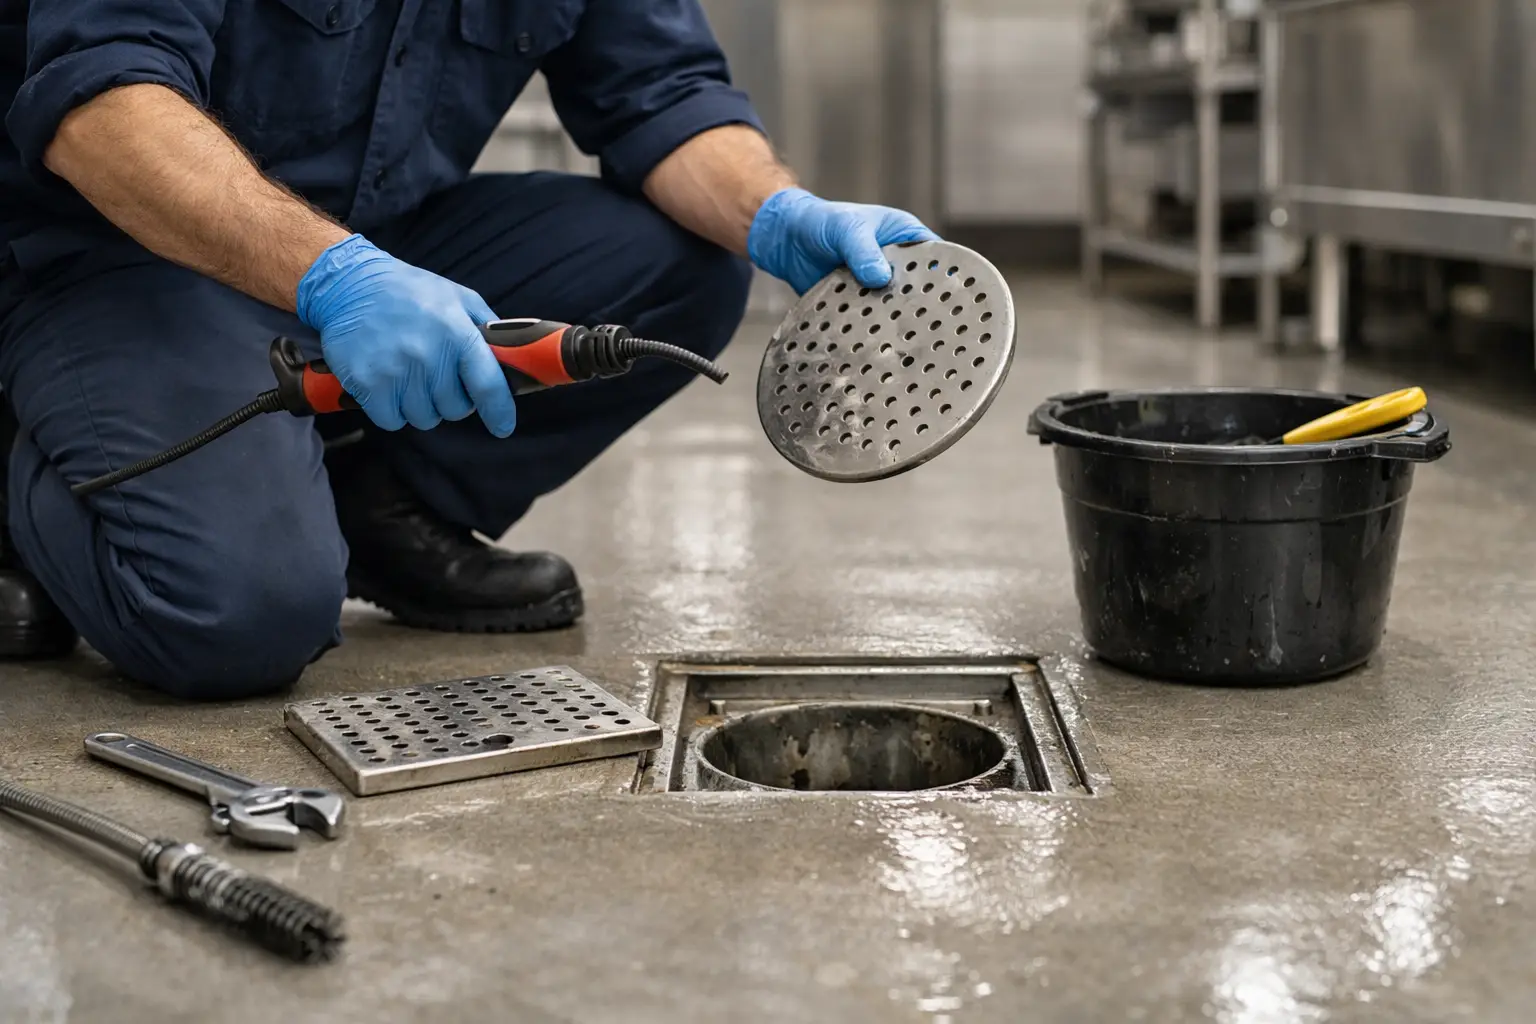
A collapsed drain rarely picks a convenient time. One day you have a slow sink or a bad smell outside, and the next you are dealing with backing up waste, damaged pipework and an insurer asking for evidence. If you are wondering are drain repairs covered by insurance, the honest answer is sometimes – but it depends on what caused the damage, where the pipe is, and how quickly the problem was reported.
Most policies do not treat all drainage issues the same. A sudden insured event is very different from a long-term maintenance problem. That distinction is where most claims are either accepted or knocked back.
Are drain repairs covered by insurance in the UK?
In many cases, yes, drain repairs can be covered under buildings insurance. But insurers usually pay for damage caused by a specific event rather than general wear and tear. If a drain has cracked because of ground movement, tree root ingress, an accidental impact or another insured cause, there is a stronger chance of cover. If the pipe has simply deteriorated over time or has been left with a known defect, that is less likely to be included.
This is where homeowners and landlords often get caught out. They assume any underground pipe failure should fall under insurance, but insurers look closely at liability and cause. A blocked drain from fat build-up is not the same thing as a fractured pipe caused by a nearby vehicle load or subsidence.
The wording in your own policy matters. Some providers include accidental damage as standard, while others make it an optional extra. Some define underground services clearly, while others are more restrictive. It is worth checking the section covering drains, pipes, cables and tanks serving the property.
What insurers usually do cover
Insurance is generally there for unforeseen damage. So if a previously sound drain becomes damaged because of a sudden or identifiable event, you may have grounds to claim.
Common examples include cracked or collapsed pipework caused by subsidence, heave or landslip. Root ingress can also be covered in some cases, particularly where roots have entered through a defect and caused structural damage. Accidental damage may apply if building works, heavy vehicles or excavation have harmed the drain. Storm-related issues can sometimes be covered too, though insurers will still ask whether the pipe itself failed due to age before the weather made things worse.
There are also situations where the insurer may cover the cost of locating the problem, not just repairing it. A CCTV drain survey often becomes important here because it provides visual evidence of the defect, the pipe condition and the likely cause. If a claim depends on proving that the issue is structural rather than routine blockage, proper diagnosis makes a real difference.
What is usually excluded
The most common exclusions are wear and tear, lack of maintenance and gradual deterioration. If a drain has been in poor condition for years, with repeated warning signs, insurers may class it as a maintenance issue rather than an insured event.
Simple blockages are another grey area. If the drain only needs unblocking because of wipes, grease, scale or general misuse, that is usually treated as routine maintenance. The same goes for pipes that have become silted up over time without a specific damaging event.
Poor installation can also be excluded. If the drain was laid incorrectly, lacked proper falls, used unsuitable materials or was damaged by defective workmanship, the insurer may say the problem stems from construction rather than an insurable risk. The same can apply if an extension or renovation has interfered with the drainage system.
That does not mean there is never any cover. It means the facts matter. A drain might be blocked and broken at the same time. One part of the issue may be maintenance, while another is genuine structural damage.
The key question is not the blockage – it is the cause
When customers ask whether insurance will pay, the first step is always to establish what has actually happened underground. A bad smell, slow drainage or repeated backups are symptoms. They are not the diagnosis.
This is why insurers often ask for evidence before approving repairs. They want to know whether the problem is a fracture, displacement, root ingress, collapse, joint failure or a basic obstruction. They also want to know whether the damage is isolated or part of a larger pattern of neglect.
A proper inspection helps separate a temporary issue from a structural fault. In practical terms, that often means a CCTV survey followed by a clear report and footage. For insurers, guesswork is no use. For property owners, it prevents paying for the wrong fix.
What to do before you contact your insurer
If sewage is backing up or the system is not functioning safely, the immediate priority is to make the area safe and stop things getting worse. Emergency attendance may be needed to relieve the blockage or contain overflow, but it is sensible to preserve evidence where possible.
Take photographs of affected areas, including external covers, flooding, damage inside the property and any visible cracks. Make notes of when the issue started, whether it has happened before and what symptoms you noticed. If there has been recent building work, heavy traffic over the drain run, or signs of ground movement, note that as well.
Then check your policy wording. Look for sections on underground services, accidental damage, escape of water, subsidence and trace and access. If the language is unclear, contact the insurer and ask specifically whether external drains serving the property are included.
A specialist drainage contractor can then inspect the system properly. This matters because insurers respond better to evidence than assumptions. A clear diagnosis, backed by CCTV footage and a written report, gives you something concrete to submit rather than simply saying the drains have failed.
Why evidence matters in a drainage claim
Drain problems are hidden by nature. Unlike a smashed window or a damaged roof tile, the fault is usually underground. That makes evidence central to any claim.
A good report should set out where the defect is, what type of damage is present, how severe it is and the likely cause. It should also explain the recommended repair method. In some cases, that may be excavation and replacement. In others, no-dig solutions such as CIPP relining can restore the pipe without digging up large sections of driveway, garden or flooring.
Insurers tend to look more favourably on a claim when the repair recommendation is proportionate and technically sound. They do not want vague statements or unnecessary work. They want to know the problem has been identified correctly and that the repair addresses the root cause, not just the symptom.
That is one reason many customers prefer to use a specialist rather than a general contractor. Diagnosis-led work is more useful than trial and error, especially if an insurer, loss adjuster or surveyor is going to review the paperwork later.
Homeowners, landlords and buyers all face different insurance issues
For homeowners, the main concern is usually whether the policy covers repairs to drains within the property boundary. For landlords, there is the added issue of tenant reports, delays and proving the problem was not caused by neglect. If drainage defects have been allowed to continue for months, insurers may be less sympathetic.
Property buyers face a different problem. A survey may flag drainage concerns before completion, but there is no guarantee that an existing owner can make a successful claim. In those cases, a pre-purchase CCTV survey can be worth far more than a hopeful assumption about insurance.
Commercial premises can be more complex again, particularly where responsibility for shared drains, lease obligations or interruption to trading come into play. The pipe may be damaged, but the first question is often who actually owns that section and who is meant to insure it.
When a repair may still be worth doing even without cover
Not every drain issue is claimable, but that does not make it minor. Leaving a damaged pipe in place often leads to repeat blockages, foul odours, water ingress and eventual ground instability. A small defect underground can turn into a larger and more expensive job if it is ignored.
The better approach is to get clear answers early. If the damage is covered, you have the evidence ready. If it is not, you can still choose the most effective repair rather than spending money on repeated call-outs that never solve the underlying problem.
For customers across the West Midlands, that usually means looking for a contractor who can diagnose, report and repair in one place instead of passing the issue from one firm to another. West Midlands Drainage deals with this kind of situation regularly, especially where customers need straightforward advice, rapid attendance and paperwork that stands up to insurer scrutiny.
A straight answer to a common question
So, are drain repairs covered by insurance? Sometimes yes, sometimes no. If the damage is sudden, accidental or linked to an insured event, there is a decent chance. If it comes down to age, neglect, misuse or poor installation, cover is less likely.
The best next step is not to guess. Get the drain inspected properly, get the cause confirmed, and make decisions based on evidence. When the problem is underground, a clear diagnosis is what gives you the best chance of either a successful claim or a repair that is done properly the first time.